for nonprofits
Can a Fiscally Sponsored Project Take In-Kind Gifts?
Yes. The tax deduction comes from the sponsor's 501(c)(3) status, and that doesn't change based on whether the gift is cash or a physical item.
Panos Kokmotos |
Can a Fiscally Sponsored Project Take In-Kind Gifts?
Yes. A project operating under fiscal sponsorship can receive tax-deductible in-kind donations the same way it receives cash, because the deduction depends on the sponsor's 501(c)(3) status, not on what form the gift takes. The donor is legally giving to the sponsoring organization, which then directs the gift to the sponsored project, and that mechanism doesn't change whether the check is for $500 or the gift is a box of supplies.
Why the tax treatment doesn't care about cash vs. property
Donors can only claim a deduction when they give to an organization the IRS recognizes as tax-exempt under Section 501(c)(3), a point the National Council of Nonprofits explains plainly: fiscal sponsorship lets "a program or organization that does not itself qualify as tax-exempt... attract funding for its operations that will, through the fiscal sponsor, be tax-deductible to donors." That sentence doesn't distinguish between money and property, because the IRS rule it's built on doesn't either. What makes any gift deductible is who receives it, not what it is.
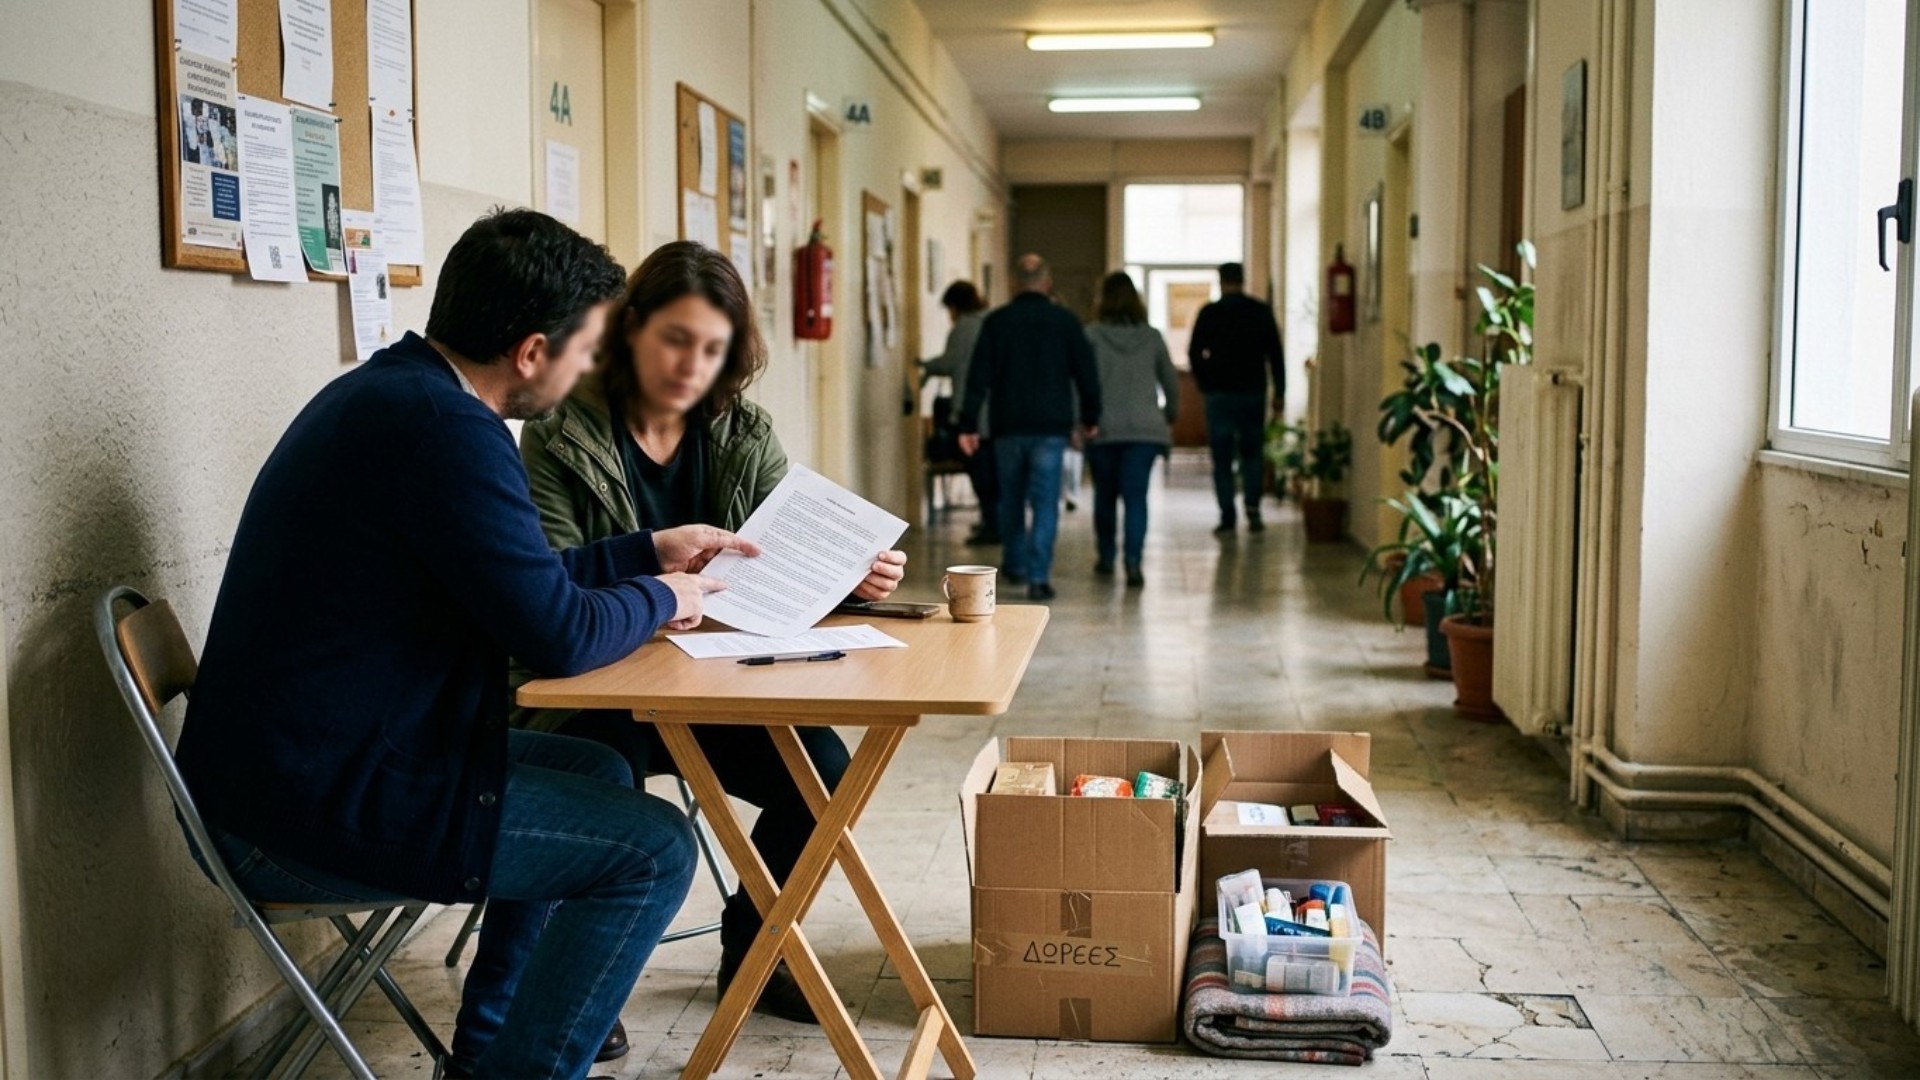
In practice, that means a donated laptop, a pallet of supplies, or a load of building materials for a sponsored project follows the same acknowledgment path as a check: the sponsor is the legal recipient, the sponsor issues the acknowledgment, and the sponsor is responsible for reporting it. The project itself doesn't need its own EIN or its own 501(c)(3) determination letter to make that gift deductible.
Where this actually gets confirmed
Not every fiscal sponsor handles in-kind gifts the same way in practice, even though the underlying tax mechanism is identical. Some sponsors are set up to process property donations smoothly, with their own intake and acknowledgment process ready to go. Others primarily handle cash and haven't built out a process for goods, which doesn't make an in-kind gift any less legally valid, but can mean more back-and-forth to get it acknowledged correctly.
Before a sponsored project promotes an in-kind wishlist to donors, it's worth a direct conversation with the sponsor: how they want in-kind gifts routed, what documentation they'll issue, and whether there's a size or type of donation they'd rather not receive directly. This is a five-minute conversation that avoids a donor getting an acknowledgment letter that doesn't match what they actually gave.
The two fiscal sponsorship models, and what each means for goods
Sponsorship arrangements generally fall into two structures. In a comprehensive model, the sponsor absorbs the project fully, often handling payroll, providing office space, and owning the resulting work; here in-kind gifts function exactly like a gift to any of the sponsor's own programs. In a pre-approved grant relationship, the sponsor funds a separate legal entity only once donor money comes in, a structure built specifically for projects that aren't yet their own 501(c)(3) but need donors to get a deduction now. In-kind gifts work under this model too, since the deductibility still flows from the sponsor's status, but the routing (does the item ship to the sponsor, or does the sponsor simply acknowledge a gift that shipped straight to the project) is exactly the kind of detail to confirm upfront rather than assume.
Why this matters for a new or grassroots group specifically
Groups considering fiscal sponsorship are often too new, too small, or too likely to wind down within a year or two to justify the cost and paperwork of forming their own 501(c)(3). That's precisely the stage where in-kind support, a founder's employer donating equipment, a local business giving supplies, matters most, because cash runway is thinnest right then. Knowing that a sponsor's status covers those donations too means a new project doesn't have to tell an early supporter to wait, or to give cash instead of the actual item they had on hand to give.
Finding a sponsor that's actually a fit
Not every fiscal sponsor works with every kind of project. Some specialize by cause area, arts organizations, environmental work, disaster response, and are set up to handle the kinds of gifts typical to that space. Others are generalists that will sponsor almost any charitable purpose but offer a lighter administrative touch in return for a lower fee. Before committing, ask a prospective sponsor three concrete things: what percentage fee they take (the Fiscal Sponsor Directory puts the most common range at 5% to 10% of project revenue, with fees up to 15% or more mostly limited to government-funded projects), whether they've sponsored a project that collected in-kind or physical donations before, and how quickly they turn around donor acknowledgments once a gift comes in. A sponsor that answers the third question with a specific process, rather than "we'll figure it out," is the one that won't leave a donor waiting on paperwork for their first in-kind gift.
FAQ
Does the sponsored project need to be listed by name on the donation receipt? Typically yes, sponsors commonly note the specific project or program the gift supports, even though the sponsor is the legal recipient for tax purposes. Confirm the exact wording your sponsor uses before promising donors anything specific.
Can a sponsored project post a public wishlist under its own name? Generally yes, since the wishlist is a fundraising tool, not a legal filing. Just make sure any donor-facing materials are accurate about which organization is the actual tax-exempt recipient.
What if our sponsor has never processed an in-kind gift before? Ask them directly rather than assuming it's not possible. The tax mechanism supports it; what varies is whether a given sponsor has an existing process ready or needs to build one for your project's first in-kind gift.
Is there a dollar limit on in-kind gifts under fiscal sponsorship? The fiscal sponsorship structure itself doesn't impose one. Normal IRS substantiation rules for large noncash gifts still apply to the donor, the same as they would for a gift to any 501(c)(3) directly.
See how a nonprofit or sponsored project can post specific in-kind needs and track exactly what's been fulfilled. Learn how Givelink works or browse the current directory of participating organizations.
See also
What is Givelink?
Learn from the founders:
Run a nonprofit? Get what you need.
Set your nonprofit up yourself in about 15 minutes. It's free, there's no contract, and you don't need to talk to anyone first.